Water, Water Everywhere: Preparing Your Home Insurance for the Late-February Thaw
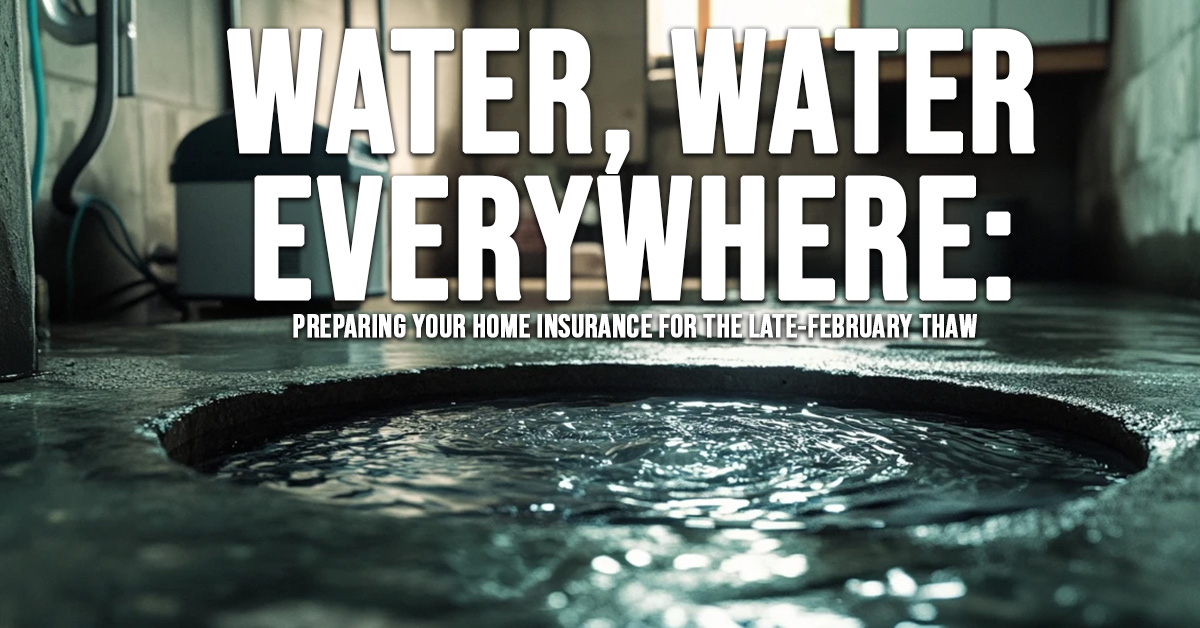
Water, Water Everywhere: Preparing Your Home Insurance for the Late-February Thaw
The final weeks of February represent a dangerous transition period for homeowners. While the “Deep Freeze” of January is behind us, the “Great Thaw” brings its own set of structural and financial risks. As temperatures fluctuate, the accumulated snow melts rapidly, and the frozen ground—unable to absorb the runoff—directs that water toward the most vulnerable part of your property: the foundation.
For many, this is the time when the sump pump, which may have been dormant for months, is suddenly forced into high gear. If it fails, or if the water volume simply becomes too much, the resulting basement flood can cause tens of thousands of dollars in damage. The most critical thing to know this February is that your Standard Home Insurance policy likely excludes this type of damage.
The Sump Pump Gap: Water Backup vs. Flood
Most homeowners assume that if water enters their home, it’s covered. However, insurance carriers differentiate between where the water comes from:
- Flood Insurance: This covers water that enters from the ground up (e.g., a nearby stream overflowing or excessive surface water rushing into your home). This is a separate policy entirely.
- Water Backup and Sump Pump Overflow: This covers water that enters the home through a sewer, drain, or a sump pump pit that has failed or overflowed. This is an optional endorsement.
If you do not have a specific Water Backup Endorsement on your policy, and your sump pump fails on a rainy Tuesday in late February, you will be responsible for 100% of the cleanup and repair costs.
Calculating the Risk and the Cost
The cost of adding a Water Backup endorsement is typically very low—often between $50 and $150 per year—yet it provides coverage for:
- Professional water extraction and drying.
- Mold remediation (which is critical in a damp basement).
- Replacement of ruined drywall, flooring, and personal property (like the gym equipment or furniture in your basement).
When choosing your limit, consider the cost of finishing a basement. A $$5,000$ limit is rarely enough if you have a finished space; most experts recommend at least a $$10,000$ to $$25,000$ limit for finished basements in flood-prone regions.
February Maintenance: Preventing the Claim
While insurance is your safety net, prevention is your first line of defense:
- Test the Pump: Pour a five-gallon bucket of water into the sump pit to ensure the float switch activates and the pump clears the water.
- Install a Battery Backup: Power outages often accompany late-winter storms. A battery-powered backup pump ensures protection even when the grid goes down.
- Check the Discharge Line: Ensure the pipe carrying water away from your house isn’t frozen or clogged with debris.
This February, don’t wait for the water to start rising. Review your policy for the Water Backup endorsement, test your equipment, and ensure that the “Great Thaw” doesn’t turn into a great financial loss for your family.
Do you have questions about your insurance? Find an insurance agent near you with our Agent Finder
Search All Blogs
Read More Blogs
Finishing the Year Strong: How to Reset Your Habits and Mindset for the Final Quarter
Reset your personal goals and finish the final quarter of the year with renewed focus and energy.
The Annual Commercial Review: 5 Questions Every Business Owner Should Ask Their Agent
Conduct a thorough annual insurance audit to ensure your business is fully protected heading into the new year.
Estate Planning 101: How Life Insurance Helps You Pass Wealth to the Next Generation
Explore estate planning strategies and how properly structured life insurance simplifies wealth transfer to heirs.
Maximizing Your Auto Discounts: Bundling, Good Driver Credits, and Paperless Savings
Discover simple ways to unlock hidden auto insurance discounts and lower your monthly bills.
Reviewing Your Umbrella: Do You Need Personal Liability Protection Beyond Your Home Policy?
Protect your personal net worth and future earnings with a high-limit personal umbrella insurance policy.
Hitting the Trails: Why October Is the Ultimate Month for Hiking and Outdoor Exploration
Make the most of autumn weather with tips for safe, scenic weekend hiking and outdoor adventures.
Umbrella Policies for Businesses: Adding an Extra Layer of Defense Against Major Lawsuits
Shield your business assets from massive liability claims with a commercial umbrella policy.
Business Continuity Planning: Using Key Person Life Insurance to Protect Your Enterprise
Safeguard your company’s financial stability and continuity with strategic key person life insurance.
Understanding Uninsured Motorist Coverage: The Hidden Shield on Your Auto Policy
Protect yourself from reckless drivers with comprehensive uninsured motorist policy coverage.
Smart Home Tech and Insurance Discounts: How Automation Lowers Your Premiums
Lower your home insurance bills by integrating smart home monitoring and safety technology.