Customizing Cold Protection: Essential Auto Insurance Endorsements for Winter Driving
Customizing Cold Protection: Essential Auto Insurance Endorsements for Winter Driving
In December, the risks we face on the road are unique, demanding more than just the basic levels of collision and liability. For drivers who have recently purchased a new car, or who invest heavily in winterization and accessories, several specialized Auto Insurance Endorsements move from optional to essential. These endorsements customize your coverage to match the true financial risk you carry on the icy roads.
- Gap Insurance: Protecting New Purchases
December is a peak month for buying new vehicles, capitalizing on year-end sales. If you finance or lease a new car, you immediately face a common financial peril: Negative Equity, also known as the “gap.”
A new vehicle depreciates significantly the moment it leaves the lot. If you total a financed car in a December accident, the insurance payout (Actual Cash Value) might be less than the remaining loan balance. This “gap” leaves you writing a check to the lender for a car you no longer own.
Gap Insurance (Guaranteed Asset Protection) is a simple, low-cost endorsement that covers this difference. It ensures that if your new vehicle is totaled, your insurance pays the full loan amount, not just the depreciated value, providing a complete financial clean slate.
- OEM Parts Endorsement: Quality Repairs
If your vehicle is damaged in a December accident and requires repair, your standard policy likely allows the repair shop to use Aftermarket (non-Original Equipment Manufacturer) parts. While cheaper, these parts can sometimes affect the vehicle’s resale value, fit, or structural integrity compared to OEM parts.
An OEM Parts Endorsement ensures that in the event of a covered claim, the insurance company will only authorize the use of brand-new parts supplied by the original manufacturer. This is particularly valuable for newer, high-end, or specialized vehicles, protecting the integrity and value of your investment during winter repairs.
- Customized Equipment Coverage: Beyond the Basics
Many drivers outfit their vehicles for the rigors of winter travel. This might include:
- Expensive, dedicated snow tires and rims.
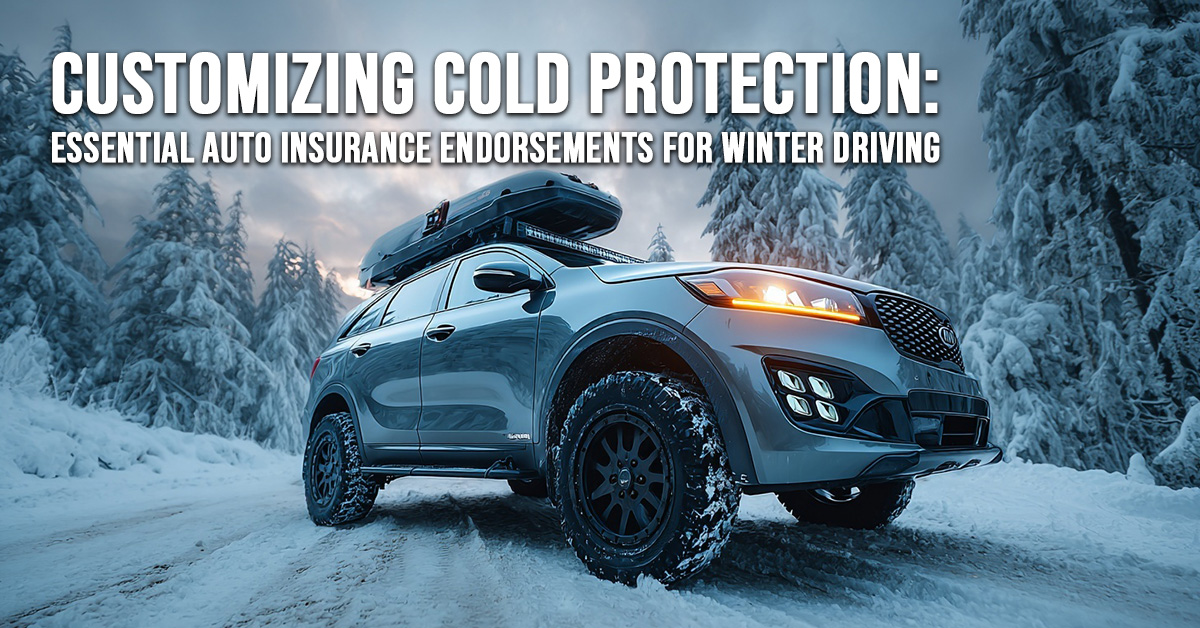
- Aftermarket roof racks, ski boxes, and cargo containers.
- Specialized suspension or cold-weather electronics.
Standard Comprehensive and Collision coverage generally only covers parts that came from the factory. If your $2,000 roof-mounted ski box is damaged in an accident or stolen, your basic policy may offer little to no compensation.
A Customized Equipment Endorsement increases the coverage limit for non-factory installed additions. This ensures that the money you invest in making your vehicle winter-ready is protected in the event of a loss, whether that loss is due to an icy collision or theft at the resort parking lot.
Don’t let the simplicity of your standard auto policy leave you financially exposed this December. Review your vehicle’s age and your investment in accessories. Adding these specialized endorsements is the key to ensuring your coverage is as robust as your winter driving preparation.
Do you have questions about your insurance? Find an insurance agent near you with our Agent Finder
Search All Blogs
Read More Blogs
Cultivating Mid-September Wellness and Routine Resilience
Discover how to establish balanced autumn routines, maintain nutritional vitality with protein-forward habits, and enjoy the refreshing energy of mid-September.
Commercial Risk Management
Business leaders can secure fourth-quarter operations by conducting mid-September audits of commercial property, liability, and business interruption policies.
Family Financial Planning
Utilize the steady pace of mid-September to assess your life insurance coverage, evaluate income replacement needs, and secure your family’s financial future.
Road Safety and Vehicle Maintenance
Navigate mid-September roadway dynamics with confidence by optimizing your auto insurance policy, checking vehicle safety systems, and preparing for changing driving conditions.

Property Security and Weatherproofing
Ensure complete residential resilience by clearing perimeter debris, inspecting weather seals, and verifying appropriate insurance coverage limits as September progresses.

Cultivating Autumn Wellness and Daily Routines
Discover how to establish balanced autumn routines, maintain nutritional vitality with protein-forward habits, and enjoy the refreshing energy of mid-September.

Mid-Quarter Risk Management and Operational Resilience
Business leaders can ensure fourth-quarter stability by conducting mid-September audits of commercial property, liability, and business interruption policies.

Mid-Year Financial Reviews and Family Security
Utilize the steady pace of mid-September to evaluate your life insurance coverage, assess income replacement needs, and safeguard your household’s financial future.

Managing Mid-September Traffic Density and Vehicle Readiness
Navigate increased September traffic and shifting roadway conditions by optimizing your auto insurance policy and ensuring peak mechanical vehicle readiness.

Post-Labor Day Property Maintenance and Autumn Preparation
Transition your property protection into mid-September by addressing post-summer wear, clearing drainage systems, and verifying adequate replacement cost coverage.