Fortifying Your Dwelling for the Autumn Transition
Fortifying Your Dwelling for the Autumn Transition
As the final week of August gives way to the opening days of September—spanning August 31 through September 4, 2026—homeowners face a critical seasonal window. Framed immediately by the approach of the Labor Day holiday weekend, this transitional period serves as an ideal checkpoint for residential property management. While summer brings its own distinct environmental stresses—such as severe convective storms, high winds, and intense UV exposure—the transition into autumn introduces entirely new risk factors that demand proactive attention and a thorough review of your homeowners insurance policy.
Assessing Seasonal Property Vulnerabilities
The shift from summer to autumn is a time of immense environmental change. Trees begin their slow cycle toward dormancy, shedding dry branches and, eventually, heavy blankets of foliage. For homeowners, this means that the immediate perimeter of the dwelling requires rigorous maintenance to prevent preventable property claims.
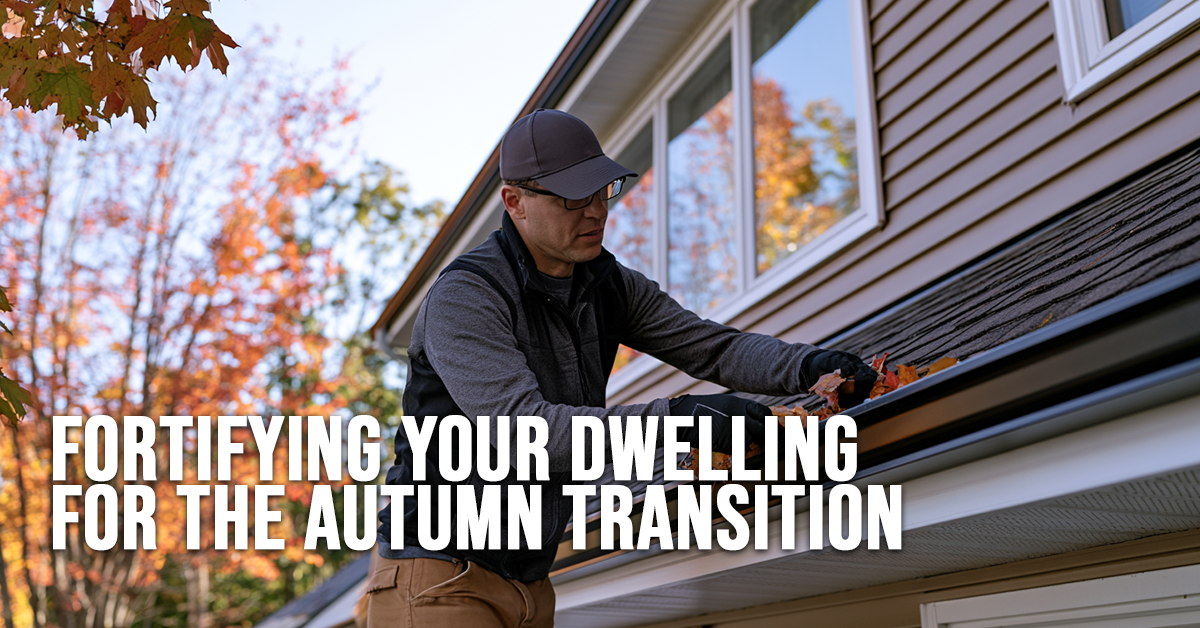
- Gutter and Drainage Management: Accumulated summer debris, from windblown twigs to dust and organic matter, frequently clogs drainage systems. Ensuring that gutters and downspouts are completely clear before autumnal rains and early freezes arrive prevents water from backing up beneath roof shingles or pooling against the foundation, mitigating the risk of costly interior water damage and basement flooding.
- Roof and Siding Inspections: High summer temperatures can warp or crack roofing materials and exterior caulking. Inspecting flashing around chimneys, skylights, and vent pipes before seasonal storms set in helps eliminate minor vulnerabilities before they escalate into major structural leaks.
- Perimeter Tree Maintenance: Overhanging branches that brushed lazily against roofs during summer storms can become heavy hazards when weighed down by early autumn winds or seasonal ice. Trimming back compromised limbs protects both your roof structure and overhead utility lines.
Reviewing Policy Limits in a Shifting Economic Landscape
Beyond physical maintenance, this early seasonal transition is the optimal time to review the financial framework protecting your home. Replacement cost valuations fluctuate due to shifts in construction material expenses and local labor rates. A policy that provided adequate coverage two or three years ago may leave a property dangerously underinsured today in the event of a total loss.
- Actual Cash Value vs. Replacement Cost: Ensure your policy is structured around guaranteed or extended replacement cost endorsements rather than actual cash value, which factors in depreciation and can leave significant financial gaps when rebuilding.
- Endorsements and Riders: Evaluate whether your current lifestyle or property additions require specialized endorsements. Home offices, high-value personal property, and specialized water backup riders often require explicit additions to a standard HO-3 or HO-5 policy to ensure seamless coverage.
By pairing physical property hardening with a meticulous financial policy review during the first weekly cycle, homeowners establish a resilient baseline that protects their most valuable asset against the uncertainties of the changing seasons.
Do you have questions about your insurance? Find an insurance agent near you with our Agent Finder
Search All Blogs
Read More Blogs
The High Cost of Building: Why Your Home Replacement Value Needs an Update This Year
Ensure your home rebuilding limits keep pace with current construction inflation rates.
The October Weekend Checklist: Smart Home Maintenance Projects Before the Freeze
Get your home winter-ready with this practical, step-by-step October weekend maintenance checklist.
Defending the Digital Frontier: Why Every Small Business Needs Cyber Liability Insurance
Safeguard your company’s digital assets and customer data against modern cyber threats and ransomware.
Term vs. Permanent Life Insurance: Choosing the Right Strategy for Your Life Stage
Compare term and permanent life insurance options to find the ideal fit for your current life stage.
Decoding Deductibles: How to Balance Out-of-Pocket Risk and Monthly Premiums on Your Car Insurance
Master auto insurance deductibles to strike the ideal balance between monthly savings and claim protection.
Spotting the Gaps: Why Standard HO-3 Policies Aren’t Enough for Today’s Homeowners
Close coverage gaps in your homeowners policy with these essential property endorsement strategies.
Embracing Autumn’s Rhythm: Practical Ways to Reset, Refresh, and Prepare Your Life for the Season Ahead
Refresh your routine this fall with practical tips for seasonal organization, wellness, and mindful living.
Strengthening Your Enterprise: Essential Commercial Insurance Strategies for Modern Business Owners
Essential commercial insurance insights to safeguard your business assets, employees, and digital operations.
More Than a Safety Net: Why Life Insurance Is a Core Pillar of Comprehensive Family Financial Planning
Learn how modern life insurance strategies protect your family’s financial future and secure generational stability.
How Telematics, Advanced Vehicle Tech, and New Rates Are Reshaping Auto Insurance
Master auto insurance trends this fall with expert insights on telematics, EV repair costs, and maximizing driver discounts.