Contributory/Comparative Negligence
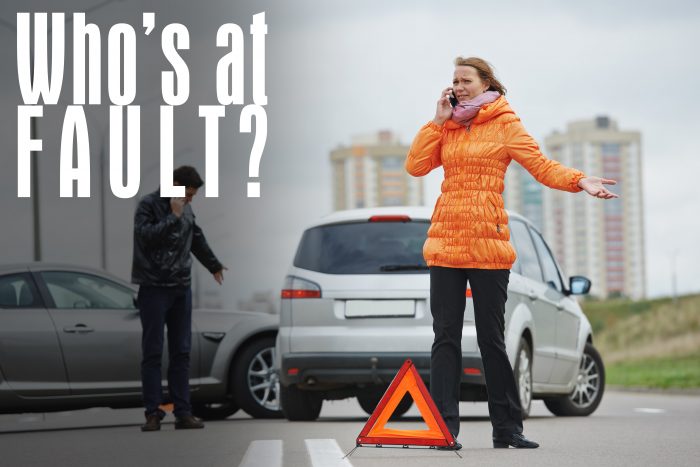
If you get into an accident that “wasn’t” your fault, it’s likely you’ll assume you won’t have to suffer any consequences. Think again.
Any amount of fault that is on your hands can reduce the amount of compensation you’ll receive for the accident. This is a law that deals with Contributory and Comparative Negligence.
There are many states that follow this law when dealing with car accidents. If you’ve never heard of this, it’s important to know about it. Here’s a quick rundown on the two concepts.
Contributory Negligence: If you were at all contributory to the cause of the accident, you are considered slightly at fault. Therefore, you will not win in court against a driver who you assumed is absolutely at fault because of this law.
This can be unfair in some cases, which caused the development of Comparative Negligence.
Comparative Negligence: This considers the negligence of all parties involved in the accident. If you were yielding to make a left turn, and you incorrectly judged the speed of oncoming traffic, resulting in a collision, you are both at fault to a certain percentage. That exact percentage is determined with Comparative Negligence and reduces your compensation if you are slightly at fault and injured in an accident.
These laws strongly encourage you to practice safe driving on the roads. Fault and compensation may not be what you are expecting.
 By: KayLynn
Do you have questions about your insurance? Find an insurance agent near you with our Agent Finder
Search All Blogs
Read More Insurance Blogs
Term vs. Permanent Life Insurance: Choosing the Right Strategy for Your Life Stage
Compare term and permanent life insurance options to find the ideal fit for your current life stage.
More Than a Safety Net: Why Life Insurance Is a Core Pillar of Comprehensive Family Financial Planning
Learn how modern life insurance strategies protect your family’s financial future and secure generational stability.
Family Financial Strategy
Utilize the steady pace of late-September to assess your life insurance coverage, evaluate income replacement needs, and secure your family’s financial future.
Family Financial Planning
Utilize the steady pace of mid-September to assess your life insurance coverage, evaluate income replacement needs, and secure your family’s financial future.
Mid-Year Financial Reviews and Family Security
Utilize the steady pace of mid-September to evaluate your life insurance coverage, assess income replacement needs, and safeguard your household’s financial future.
Honoring Labor Day Through Long-Term Family Protection
Discover how life insurance acts as the ultimate guarantor of your daily labor, providing essential financial continuity, debt neutralization, and protection for loved ones as autumn approaches.
The Late-Summer Financial Reset
Conduct a mid-to-late-year financial reset to update your life insurance coverage, review beneficiary designations, and secure your family’s future
Beyond Income Replacement: Utilizing Permanent Life Insurance for Intergenerational Wealth Transfer
Secure your family’s financial future across generations. Discover how permanent life insurance and estate planning tools transform death benefits into lasting legacy wealth.
The Ultimate Safeguard: Designing a Life Insurance Plan That Outlasts Uncertainty
True security means knowing your family’s future is permanently protected. Discover how a comprehensive life insurance strategy secures multi-generational wealth.
The Mid-Year Financial Audit: Securing Multi-Generational Wealth Before Q4
Don’t wait until December to review your financial plan. Discover why August is the perfect month to audit your life insurance and lock in generational security.