Neglect and Homeowners Insurance
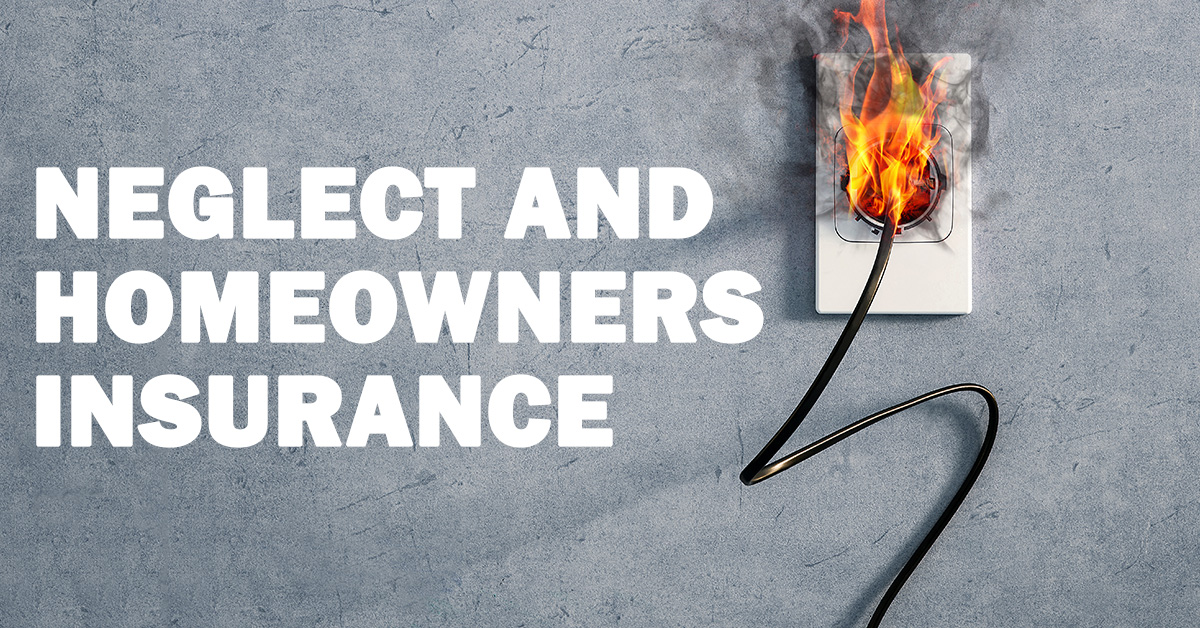
Neglect and Homeowners Insurance
The purpose of homeowners’ insurance is to help protect homeowners from losses and property damage due to covered calamities. Home insurance is actually a series of coverages that includes the main dwelling, outbuildings, personal property, and liability. Homeowners’ insurance is not intended to cover normal wear and tear, and it certainly is not designed to cover damage due to owner neglect. Here is a quick look at some examples where claims may be denied due to neglect.
Falling Tree
It is likely that damage caused by a falling tree during a storm will be covered under a home insurance policy. If that tree, however, has been diseased and leaning over a neighbor’s home and that fact was known in advance, that could be considered neglect. Diseased or dangerous trees should be removed as a part of home maintenance.
Rotting Fencing
Sure, a wooden fence that is blown down by wind or damaged when a car drives through it may be covered. A neglected fence that is rotted, rusting, or otherwise in disrepair may not be. Again, a homeowner is responsible for normal repair and replacement of aspects of their home, and neglect is not sufficient cause for a claim.
Roofing
Roofs that have been damaged by storms are likely to be covered at least on some level. Some companies are moving to prorated coverage for roofing based on the expected lifespan of the roof and how long it has been in service. If a roof has been neglected and leaks go unattended, coverage could potentially be denied.
Home insurance is not intended as a replacement for routine home maintenance. It is important that homeowners keep properties well maintained and repaired.
If you have questions about home insurance and what is and isn’t routinely covered, please feel free to give us a call. As independent insurance agents, we are qualified to review home insurance policies issued by any company. If you like, we can then search our network of companies to find coverage to suit your situation and your budget. Reach out to us today and get started.
Do you have questions about your insurance? Find an insurance agent near you with our Agent Finder
Search All Blogs
Read More Blogs
More Than a Safety Net: Why Life Insurance Is a Core Pillar of Comprehensive Family Financial Planning
Learn how modern life insurance strategies protect your family’s financial future and secure generational stability.
How Telematics, Advanced Vehicle Tech, and New Rates Are Reshaping Auto Insurance
Master auto insurance trends this fall with expert insights on telematics, EV repair costs, and maximizing driver discounts.
Protecting Your Investment Amid Shifting Climate Realities
Essential tips for updating home coverage, handling rebuild inflation, and securing the best rates this fall.
Cultivating Wellness and Equinox Balance
Discover how to establish balanced autumn routines, maintain nutritional vitality with protein-forward habits, and enjoy the refreshing energy of the equinox transition.
Commercial Risk Management
Business leaders can secure fourth-quarter operations by conducting late-September audits of commercial property, liability, and business interruption policies.
Family Financial Strategy
Utilize the steady pace of late-September to assess your life insurance coverage, evaluate income replacement needs, and secure your family’s financial future.
Road Readiness and Commuter Safety
Navigate late-September traffic and cooling morning temperatures by optimizing your auto insurance policy, checking vehicle safety systems, and preparing for autumn roadways.
Property Hardening and Final Autumn Prep
Ensure complete residential resilience ahead of the equinox by finalizing gutter clearing, testing heating systems, and verifying replacement cost policy limits.
Cultivating Mid-September Wellness and Routine Resilience
Discover how to establish balanced autumn routines, maintain nutritional vitality with protein-forward habits, and enjoy the refreshing energy of mid-September.
Commercial Risk Management
Business leaders can secure fourth-quarter operations by conducting mid-September audits of commercial property, liability, and business interruption policies.